The Pay Yourself First Budgeting Method: A Step-by-Step Guide for Beginners
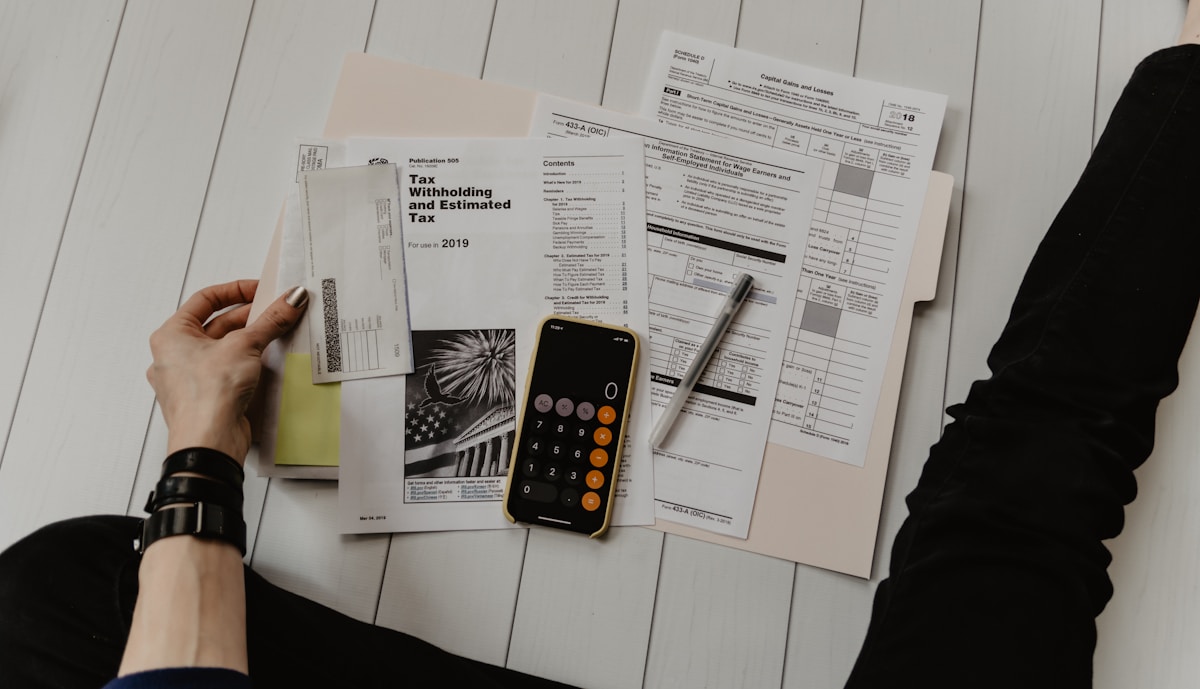
- Primary Signal: The Pay Yourself First Budgeting Method: A Step-by-Step Guide for Beginners
- Overview: The pay yourself first method flips the usual budgeting order: savings leave your account on payday, and you budget with what remains. This step-by-step guide shows how to pick a s...
- Verification: Analyzed and compiled by Free2Rich Vault editorial monitoring desk.
Most people budget backwards: they spend through the month and save whatever happens to be left, which is usually nothing. The pay yourself first method flips that order. Savings come out of your pay before anything else, and the rest of the month is budgeted with what remains. It is a simple change, but it is the reason some people build savings steadily on modest incomes while others, earning more, save nothing at all.
Pay yourself first means treating savings as the first bill you pay each pay period, not the last. As soon as income arrives, a fixed amount or percentage moves into savings or investments, and only then do you allocate money to rent, groceries, bills, and discretionary spending. The idea is psychological as much as financial: money you never see is money you do not miss, while money sitting in your checking account will always find something to be spent on. The method works with any income level, because the percentage can be adjusted, and it works with any savings goal, from an emergency fund to a house deposit to retirement.
Start with your actual take-home pay, meaning the amount that lands in your account after tax and deductions such as pension contributions or health insurance. If you are employed, this figure is on your payslip. If you are self-employed, estimate it conservatively after setting aside money for tax, since overestimating take-home pay is the fastest way to build a budget that fails. Write the number down: every later step in this method depends on it. If your income varies month to month, use your lowest typical month as the baseline and treat stronger months as bonus savings rather than spending room.
Many financial guides suggest saving ten to twenty percent of take-home pay, but the right number is the one you can sustain without constantly raiding the savings. If twenty percent feels impossible, start at five percent and raise it gradually. A useful approach is to pick a starter percentage, run it for two months, and then increase it by one or two percentage points whenever you get a pay rise or pay off a bill. The habit matters more than the starting figure: someone saving five percent consistently for years will end up ahead of someone who saves twenty percent for a month and then quits. Decide what you are saving for at the same time, since a clear goal, such as three months of expenses or a specific purchase, makes the transfer feel purposeful rather than restrictive.
Automation is the engine of the whole method. Set up a recurring transfer or direct deposit split that moves your chosen amount into savings on payday, before you have a chance to spend it. If your employer offers a direct deposit split, use it, since the money never even enters your spending account. Otherwise, schedule the transfer in your banking app for the day after payday. If you receive income irregularly, automate a fixed amount on a set date and adjust it manually in strong months. The rule is simple: if the transfer requires willpower every month, it will eventually be skipped, so remove the decision entirely.
Once the savings transfer is set, the remaining money is your real budget. Allocate it across essentials first: housing, utilities, groceries, transport, and insurance. Then allocate what is left to discretionary spending such as dining out, entertainment, and subscriptions. This step often reveals uncomfortable truths, such as a subscription stack that costs more than expected, but that is the point: the method forces spending to fit around savings rather than the other way around. If the remaining amount genuinely does not cover essentials, lower the savings percentage rather than abandoning the method or borrowing to fill the gap. A smaller, sustainable transfer beats a larger one that collapses within a month.
Pay yourself first takes about fifteen minutes to set up. Work out your take-home pay, pick a starting percentage you can live with, open or identify a separate savings account, and schedule the automatic transfer for your next payday. Then build the rest of your budget around what remains. You may barely notice the missing amount after the first month, and that is exactly the point. Over time, the habit compounds: the emergency fund fills, the deposit grows, and the stress of living from paycheck to paycheck fades. Saving is rarely about earning more; it is about deciding, once, that your future self gets paid before anyone else does.
📖 Continue Reading the Full Story
Continue reading this article on Free2Rich Vault.
⚡ Access Full Content NowMore from Free2Rich Vault

 📈 FreeRich FIRE
How to Create a Zero-Based Budget: A Step-by-Step Guide for Beginners
A zero-based budget gives every dollar of income a job before the month begins. Learn the exact steps to build...
 💎 Try2Rich
How to Buy Off Plan Property in Dubai: A Step-by-Step Guide for Foreign Buyers
Learning how to buy off plan property in Dubai is the first move for many foreign investors, thanks to staged ...
 🤖 FreeRich AI Hub
How to Use NotebookLM for Research Papers: A Step-by-Step Guide
NotebookLM (now called Gemini Notebook) is Google's free AI research assistant that answers questions using on...
 🎮 GameVault 668
How to Create a Favicon for Your Website Free: A Complete Guide
A favicon is your brand's smallest ambassador. This guide shows how to design one that reads at 16 pixels, gen...